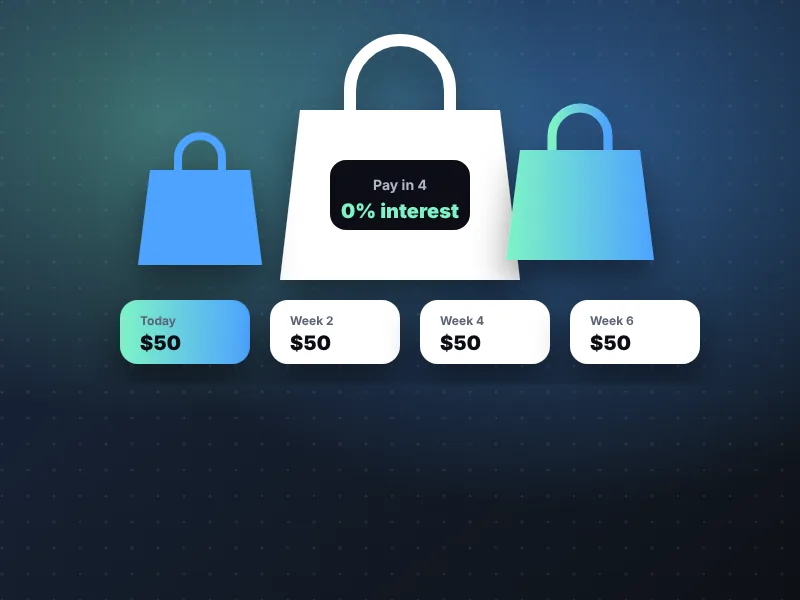
- Pay in 2, Pay in 4 and Pay in 5 are interest-free when paid on time; Monthly Payments may charge 0%–34.99% APR.
- Match the plan to the purchase: shorter plans cost less and are easier to track than long financing.
- Returns reduce your remaining installments first, and you can pay any plan off early with no penalty.
The Sezzle App offers several ways to split a purchase. Choosing the right one can mean the difference between a stress-free budget and a fee. Here is how each plan works in 2026.
Sezzle plans at a glance
| Plan | Amount range | Due at checkout | Schedule | Interest |
|---|---|---|---|---|
| Pay in 4 | $35–$2,500 | 25% | 3 more payments every 2 weeks (6 weeks) | 0% |
| Pay in 2 | $10–$500 (online) | 50% | 1 more payment in 2 weeks | 0% |
| Pay in 5 | Varies | 20% | 4 more payments every 2 weeks (8 weeks) | 0% |
| Monthly Payments | $150–$10,000 (online) | $0 | 3 months to 4 years | 0%–34.99% APR |
| SezzleCash | $50–$300 | $0 | 5 payments over ~10 weeks | Flat fee |
Pay in 4
Sezzle's flagship plan. You pay 25% at checkout and the rest in three equal installments every two weeks. On a $200 purchase that is $50 today and $50 at weeks two, four and six.
It works online and in store, and it is the best place for new users to build a track record that later unlocks Sezzle Cash.
Read nextSezzle calculator→Pay in 2
Half today, half in two weeks — available online for $10 to $500. It is ideal for small purchases timed right before payday, because the second payment lands on your next check.
Pay in 5
Offered to some shoppers, Pay in 5 lowers the upfront payment to 20% and spreads the rest over eight weeks. Smaller payments are easier on a tight budget, but you remain in debt for longer, so make sure all five dates fit your pay cycle.
Monthly Payments
For larger purchases from $150 to $10,000, Sezzle offers monthly installment loans from three months to four years with APRs from 0% to 34.99%.
Nothing is due at checkout, but this is traditional credit: a hard inquiry may apply and interest can add up. Compare the total cost with a credit union loan before choosing it.
“The shorter the plan, the less you pay overall and the less you have to track. My rule: use Pay in 2 or Pay in 4 for anything under $500, and only consider Monthly Payments for planned big-ticket items with a 0% promotional offer.”
— Marcus Reyes, Senior Writer, Payments & Fintech AppsHow to choose the right Sezzle plan
Pay in 2.
Pay in 4.
Pay in 5, if offered.
Monthly Payments at 0% APR only.
Use the Sezzle calculator to see each schedule before you buy.
Returns, early payoff and juggling several Sezzle plans
Choosing a plan is only half the story. What happens after checkout — a return, an early payoff or a second order — decides how smooth the plan feels in real life.
If you return an item
Once the merchant processes your refund, Sezzle applies it to the remaining installments on that order first. Until the refund posts, keep paying on schedule — don't assume a pending return pauses autopay.
- Keep the merchant's return confirmation in case the refund is slow to appear.
- If a payment is due before the refund lands, consider a reschedule rather than letting autopay fail.
If you want to finish early
You can pay one installment or the whole balance of Pay in 2, Pay in 4 or Pay in 5 at any time in the Sezzle App, with no penalty.
For Monthly Payments, read your loan terms on screen — paying down an interest-bearing balance sooner usually lowers the total you pay.
If you have several plans running
Each order keeps its own schedule, so two or three plans can land on the same week. Before adding a new one, open the app's payment calendar and total what is due over the next month.
A Sezzle Cash advance runs on yet another schedule, so include it in that total.
Frequently asked questions
Which Sezzle plan has no interest?
Pay in 2, Pay in 4 and Pay in 5 charge 0% interest when you pay on time. Monthly Payments may carry an APR from 0% to 34.99% depending on the offer.
Can I choose Pay in 5 for every purchase?
No. Pay in 5 is offered to some shoppers on some purchases. The plans available to you appear at checkout in the app.
Does Monthly Payments affect my credit?
It can. Opting into longer monthly financing may trigger a hard credit inquiry, and those loans may be reported to credit bureaus.
- Sezzle Inc., “Sezzle Reports Second Quarter 2026 Results”, August 6, 2026.
- Sezzle – Shop, Save, Earn, Apple App Store listing, accessed October 2026.
- NerdWallet, Sezzle review: fees, plans and credit reporting, accessed October 2026.
- Consumer Financial Protection Bureau, resources on buy now, pay later and earned-wage/cash advance products.